Showing posts with label Monetary Policy. Show all posts

Monday, 9 March 2020

Macroeconomic Pathogens


As Andrew Bailey warms up to his new office as governor of the Bank of England, he has a weather pattern that doesn’t sit well. He must wield the hand of a strained monetary policy in an upcoming Brexit world, and look to his fellow BoE economists in the impact modelling of Covid-19 on the UK. He knows the effectiveness of his institution is being tested, and as the rain pours down on thread needle street, the Dow Jones Level - 1 circuit breaker is hit.
Level 1: A drop of 7% from the prior day's closing price of the S&P 500 triggers a 15-minute trading halt. Trading is not halted if the drop occurs at or after 3:25 p.m. ET.
Level 2: A drop of 13% triggers a 15-minute halt. Trading is not halted if the drop occurs at or after 3:25 p.m. ET.
Level 3: A drop of 20% triggers a halt for the rest of the trading day, and trading resumes the following day.

Viruses and the economy

A pandemic is an interesting economic scenario, because it really has an open rule book to how it behaves, depending on the origin. It typically hits supply first, instead of demand. No matter how high the want for Parmesan cheese may be. A closed factory with a quarantined workforce in Italy will not meet the consumer demand. Take this with the additional pressure from panic buying, and we have an inverse relationship occurring.

In December, in a small district in the city of Wuhan, China. A local food market formulated, under the correct conditions Covid-19 that became the kick-starter to the correction of the world economy and largest global pathogenic outbreak in the industrialised world. Covid-19 has taken advantage of our interdependent infrastructure and supply chain. Bringing the economic might of China to a halt, and has now spread beyond borders and across the globe. Now with halted production, the dynamic borrowing small & medium enterprises in China depend on are becoming the first economic casualties.

Troubled water for the fishes

March was always going to be a difficult month. Fragile OPEC talks took place whereby leading oil producing states turned hostile in talks. Already having to deal with an economic slowdown from the virus, led to a terrible disagreement on supply cuts in order to combat the decline in oil receipts. This combined with negative data ensuing from the previous week, made markets on the 9th of March hit the circuit breakers on US indices.
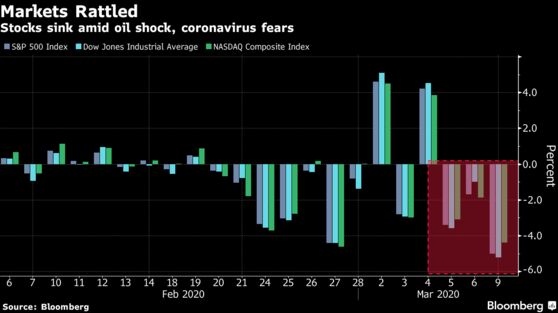

What further impact will be felt, is still early days, however these corrections will turn the portfolio manager to dive deeper into their folder and see which institutions and corporations are weak on the cash side and are “zombies” to this economic stagnation.

Airlines usually are the first ones with blood in the water and will be an interesting case with the crippled airline manufacturing issues from Boeing. However, they are hit in two ways. A reduction in sales, though also a reduction in fuel costs as now Jet fuel futures turn cheap. Yet, sales will take precedent, in combination to employee costs from the Covid-19 impact. March is the main month that fills the balance sheet and with the high ratios of the industry of net debt to Ebitda, the sharks will be circling for the bite.

Passing of the Baton to Fiscal

The last ten years has seen the largest global injection of cash into financial markets, with central banks fighting the faults of a stalling global economy. Yet, there are some human elements central bankers cannot solve, and where politicians will have no choice but to step up, as monetary policy shows its limit.

Government bonds took up the majority of the capital flight as US and European notes hit historic highs and as the fed made an emergency cut of 50 basis points, the central bankers of the world reaffirmed their position. Fiscal policy needs to step to the plate. 

Despite these warnings for many years, few economies are willing or able to act. The US congress passed a $8bn emergency corona virus response bill, to help struggling industries, though the euro-zone's export animal Germany needs to act fast, and reduce it's bickering on the purse string to the €1tn budget for the euro-zone. Despite having year-on-year fiscal surpluses Berlin has yet to relieve the several quarters of weak growth to fiscal policy. 

Closing remarks

After some further debating, OPEC will reach an agreement after their economies woo on sentiment. Yet, depending on the global fiscal response to small and medium sized industries, the a short lived bear could be an underestimation.

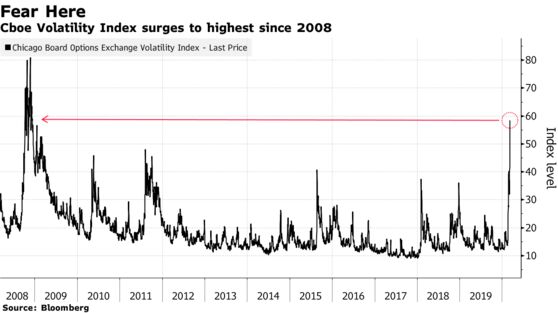
This brings me to my most beloved index. The VIX made it's comeback from the volatility and mania of 2008 on Monday, and acts as a careful reminder to governments and institutions, of the many weak spots the economy still has, if left unbalanced.



Tuesday, 1 September 2015

Super Summer, Super Thursday, Black Monday & End of Brazil's Commodity Cycle

Thursday the 6th of August signalled no change in Bank of England’s interest rate (Currently 0.5%), China’s central bank getting ready to move its weight in the direction of returning to devaluation, in order to boost exports, and from the other side of the Pacific, the looks of the US dollar strength year on year 20% bringing thoughts on the soon to be basis rate increase by the Federal Reserve.

S&P 500 Turmoil 
The major topics to be highlighted here are miscommunication and fundamental problems in the announcement of Central banks in the recent affairs of August.


Carney’s MPC

When double the information is released, as well as Mark Carney’s patented monetary trick of forward guidance, a market feels more reassured.

An 8-1 vote amongst the MPC committee, reaffirmed the near whole agreement of the current state of inflation targeting. Not only was the move concrete, it marked also the strength of the Canadian central banker’s hold at sailing the market through unknown hotspots arising.

The Forward guidance Mark Carney delivered was however the thought of many analysts; the UK economy is ‘in need in care’. The absolute truth and gut feeling for the majority, after an interesting summer change in growth levels, they know things could soon spike like a thunderbolt from the heavens, right down to the ground.

Reasons?

Most greatly mentioned is falling commodity prices, leading to lower inflation, also the continuing unknown course within the Euro-zone area, Russia and the slowdown in growth within the Far East and emerging economies. Hopefully due to this Carney could hopefully see the weighing scales to dip on either of the following two.
  •  Most consumers will decide to save, increasing MPS,
  • Consumers will be driven to consume more, due to the fall in production, fall in commodity prices, the price of goods will become less, keeping inflation positive.
As much as the second will help GDP, the first is more of a key issue, when it comes to either stagnation or end of the growth cycle.

Far East Volatility

Last week has been quite the roller coaster ride as Asian Stocks bore a significant plunge in value on Monday, then making a deep recovery by Thursday; Is this the end of Chinese volatility?

Vix Volatility Index S&P 500 

At the beginning of August, The Peoples Bank of China conducted devaluation of their international yuan currency, in order to help boost exports to deal with the crash in the Chinese markets. Though the delivery of the information was poor. The sudden unexpected change in the exchange rate policy, led to market turmoil that only calmed after clarification by the PBOC.

“China will maintain economic operations within a reasonable range”

The initial feel by the markets led to a global selloff of risky assets, as they believed it was a reaction to the abrupt deterioration in Chinese growth.
In the following days, China clarified the message by ensuring that the move they had made in devaluation was designed to

“Enhance market-orientation and benchmark status”.

The acknowledgement of poor communication had the effect of calming the markets, as the above statement gave light to moves the PBOC had made. First their purchasing of currency, the knowledge of $3.6Tr USD being in reserve, as well as US federal reserve rate hikes being on the  horizon soon enough. Domestically also the Renminbi’s real exchange rate has appreciated >25% since 2007.

Forecast

The gut feeling of analysts and my own personal assumptions, are that we can expect a steady slowdown in Chinese growth. This of course, leading to weaker demand in commodities, thereby having a knock-on effect on the Australian economy. At the end meaning, that portfolio diversification is crucial and that we should expect more surprises from China, as they grapple to deal with a crucial situation with their economy.


Economic Forecast: The Weather in Rio is looking bleak

For the body of Christ that towers over Rio, the Brazilian government also sees the world looking down. The country faces the end of its commodity growth cycle; and if that was not enough huge corruption, declining consumer confidence and preparation towards the Olympic Games.

Due to the rise in supply of oil, slowdown in emerging market production levels, and weak capital markets, Brazil is facing a dire position. The major fall of the Petrobas scandal, in its corruption and rescue cost to the economy, has only contributed more to the slowdown in economic growth and widening of the Brazilian deficit.

The situation, began by Brazil revaluating its surplus targets that sparked a selloff of Brazilian assets. Soon enough it led to an announcement by Standard & Poors, warning of the investment status being downgraded.


Brazil is desperately trying to take control of its inflation. In the last seven meetings of Brazil’s central bank, there has been an increase in interest rates each time, which now stands at 14.25%. Coupled together with two consecutive quarters of declining GDP, South America’s largest economy is now in recession.